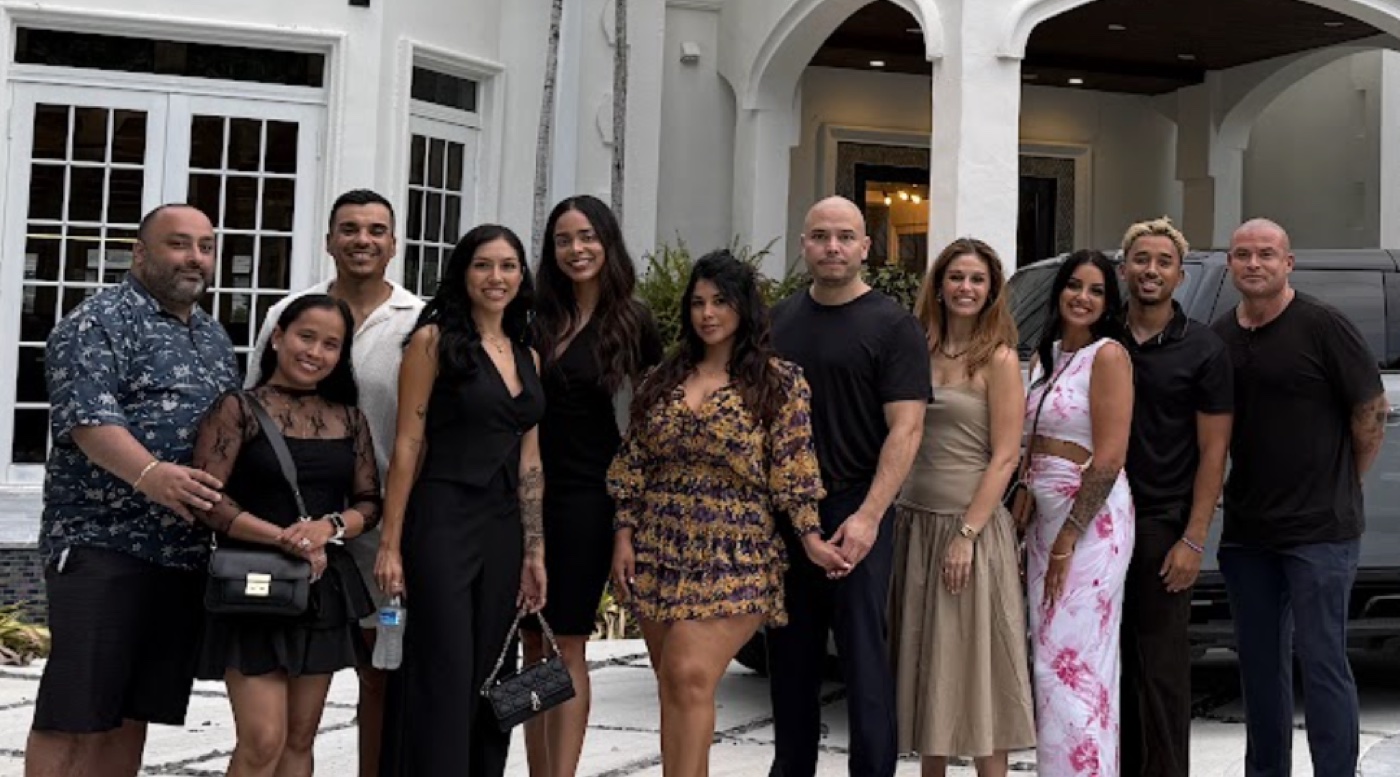
"They got me over half a million in total funding. Started with 0% cards, then layered in loans and lines of credit. Two rounds, eight products, all strategic."
View entire Capital Stack
Citizens BLOCRate set by the institution
$250,000
Amex BLOCRate set by the institution
$90,000
BofA Business CC x30%
$54,500
Chase Ink x20%
$45,000
Amex Blue Cash0%
$25,000
Amex Blue Plus0%
$25,000
Bluevine BLOCRate set by the institution
$20,000
US Bank Triple Cash0%
$15,000
This file. Eight products across six institutions. $164,500 at 0%. $360,000 in lines. Approvals, limits and terms are decided by the institutions.
Menard S.Real estate investor · Hartford, CT
$249,500 across twelve products.
"Everything you said you would do actually worked like a charm. I was surprised when we got some high limits. You just got to trust the process."
View entire Capital Stack
LightstreamRate set by the institution
$45,000
Southend Capital EquipmentRate set by the institution
$45,000
Chase Ink Unlimited0%
$41,000
KeyBank0%
$25,000
Chase Ink Cash0%
$23,000
Wells Fargo Signify0%
$22,000
BofA Customized0%
$18,500
BofA Unlimited0%
$9,000
BofA Travel0%
$9,000
US Bank Platinum0%
$8,000
Amex Blue Cash0%
$2,000
Amex Blue Plus0%
$2,000
This file. Twelve products across eight institutions. $159,500 at 0%. $90,000 term. Approvals, limits and terms are decided by the institutions.
Brandy E.Med spa owner · Philadelphia, PA
$222,000 across nine approvals.
"I don't think I would have had the connections, the relationships, and the organization to get to where I am without you guys."
View entire Capital Stack
Amex Business Platinum0%
$50,000
Chase Unlimited0%
$45,000
Amex Business Cash0%
$35,000
Chase TravelRate set by the institution
$35,000
PNC0%
$23,500
Wells Fargo Signify0%
$14,000
US Bank 12 month0%
$10,000
US Bank 18 month0%
$7,000
Truist0%
$2,500
This file. Nine approvals across six institutions. $187,000 at 0%. Approvals, limits and terms are decided by the institutions.
Dr. TruongHealthcare professional · Florida
$184,000 across six products.
"Having lines of credit and funding help not only me but every business to expand. That is very useful."
View entire Capital Stack
Bluevine BLOCRate set by the institution
$60,000
US Bank Platinum0%
$38,000
BofA x20%
$28,000
GM Goldman Sachs0%
$23,000
Amex BLOCRate set by the institution
$20,000
Chase Ink0%
$15,000
This file. Six products across six institutions. $104,000 at 0%. $80,000 in lines. Approvals, limits and terms are decided by the institutions.
Korey G.Business owner · Las Vegas, NV
$135,777 across eight products.
"Did what you said you were going to do, followed through with everything, and helped me along every step of the way. That's not like any other system."
View entire Capital Stack
LightstreamRate set by the institution
$39,777
Chase Ink0%
$21,000
Wells Fargo Signify0%
$18,000
BofA Red0%
$16,000
Wells Fargo BLOCRate set by the institution
$15,000
US Bank Platinum0%
$10,000
BofA Gray0%
$8,000
BofA BlueRate set by the institution
$8,000
This file. Eight products across five institutions. $73,000 at 0%. The number on the file is $135,777. Approvals, limits and terms are decided by the institutions.
FrankReal estate investor
$350,000 SBA loan.
View entire Capital Stack
0% card roundsPreparation
First
SBA loanLater round
$350,000
This file. Cards first, then the bank. The number on the later round is $350,000 SBA. Approvals, limits and terms are decided by the institutions.
The banks we sequence
CHASEAMERICAN EXPRESSBANK OF AMERICAWELLS FARGOU.S. BANKCITIPNCTRUIST
Two ways this goes
The wrong order costs you more than one approval.
Without an advisor
APPLICATION HISTORY 6 HARD INQUIRIES
01Application · wrong bureau pulledDENIED
02Application · compliance mismatchAUTO-DENIED
03Application · inquiry-sensitive bankDENIED
04Approval · a fraction of the maximum$8,000 LIMIT
Wrong bureau, wrong orderSix inquiries. One $8,000 card.
Applications fired in whatever order feels right, so approvals burn on wrong-bureau pulls
A 0% interest period that runs out into 29% APR with no second round prepared and no way out
A success fee of ten to twenty percent stacked on top of whatever you manage to get
One round, offshore fulfillment, done. Nobody plans what happens after the promo ends
With Stacking Capital
THE SEQUENCE ROUND ONE · LIVE
ChaseAPPROVED ✓
American ExpressAPPROVED ✓
Bank of AmericaIN REVIEW
U.S. BankSEQUENCED NEXT
The Bankable Scan finds every blocker across your personal and business credit before a single application goes out
Banks sequenced by bureau sensitivity and inquiry tolerance, applications done live on Zoom with your advisor
Inquiry cleanup and credit gardening between rounds, so the file gets stronger while the limits season
An exit plan built before round one, so the end of the 0% interest period is a step in the plan, never a cliff
REPLACES →10-20% success feesMass applicationsCredit repair subscriptionsGuess-the-bank order
Our position
A broker's success fee grows with every dollar you borrow. We built the opposite incentive.
Stacking Capital is a one on one capital advisory. The plan is built for your specific file, the applications happen live on Zoom with your advisor, and the fee is a one-time flat fee for six to twelve months of the program. The more capital we help you access, the cheaper every dollar of it gets. We went the other way on purpose.
The Bankable Blueprint™
This is the machine we build around your file.
Four phases, in the exact order they happen. You should be able to replay the whole engagement like a movie before you ever book a call.
01Phase One · Weeks 1-6
Preparation
The Bankable Scan™ Lender Compliance Credit Optimization
The Bankable Scan runs 47+ data points and finds every blocker a bank's algorithm will find... before the bank does.
Bankable Scan™ · REF-00147+ Data Points
Entity & NAP syncMISMATCH FOUND
Hard inquiries3 REMOVABLE
Utilization splitOPTIMIZE
Tier 1 bank relationshipsNOT SEASONED
Lender compliance11 + 9 ITEMS MAPPED
Credit optimization WORKSTREAM 01
Hard inquiries that never became accountsREMOVED
Utilization splitENGINEERED
Revolving profileAZEO
+
Lender compliance WORKSTREAM 02
Phase 1 · 11 items0% APPROVALS
Phase 2 · 9 itemsFULL BANKABILITY
RemediationAll 20 mapped
+
Banking foundation WORKSTREAM 03
ChaseOPENED
Wells FargoOPENED
Bank of AmericaSEASONING
Checking accounts opened and seasoned with tier one banks.
Exit plan · built before round one
The one decision that makes the end of the 0% period a step instead of a cliff.
Every compliance item we fix prevents an auto-denial. Every utilization point we optimize raises a limit. Every account we season pushes a bank closer to its maximum. The applications wait, because sending them early is the one mistake you can't undo.
Outcome.A file the algorithms can't auto-decline.
02Phase Two · The Rounds
Sequenced applications, live on Zoom
Bureau-Sensitive Ordering Credit Gardening Between Rounds
Then the applications start. The right banks, in the right order, at the right spacing... and every single one happens live on Zoom with your advisor. Between rounds we remove the hard inquiries that never became open accounts and let the new limits season.
ROUND ONE · SEQUENCED LIVE ON ZOOM
Bureau-soft bank firstAPPROVED ✓
Comparable-limit bank secondAPPROVED ✓
Inquiry-sensitive bank lastTIMED · DAY 30
BETWEEN ROUNDS · CREDIT GARDENING IN PROGRESS
Hard inquiry · never became an accountREMOVED
New limitsSEASONING · DAY 45
UtilizationREBALANCED
ROUND TWO · SEASONED WHEN THE FILE IS READY
Comparable limits now on fileSTRONGER SIGNAL
Inquiry profileCLEANED
Timing3-6 MONTHS LATER
Handled properly, round one can set up a stronger second round... depending on the file and how it seasons.
Engagement TimelineMonths 1-6
The spacing is part of the strategy, not a delay in it.
Outcome.Round one lands at the maximum your file supports, at 0%.
03Phase Three · In Parallel
The business credit build
Tradelines Business Scores Bank Rating
While the rounds run, we build the side of your file most funding shops never touch: the business itself. Real tradelines reporting, business scores climbing, and your bank rating engineered so the institutions see a company they can underwrite on its own.
10-15 tradelines reporting
Dun & Bradstreet
Experian Business
Equifax Business
Business Score BuildTargets
PAYDEXTarget 80+
IntelliscoreTarget 70+
FICO SBSSTarget 160+
The Build CurveMonths 1-6
1Tradelines reporting
2PAYDEX 80
3SBSS 160
Low 5 bank rating
04Phase Four · Graduation
The 0% period ends. The plan fires.
The Refinance Path Institutional Lending Prime-Range Rates
When the 0% interest period runs out, the exit plan you built in week one executes. The balances move, and the profile you spent six months building unlocks the institutional side of the market. The cards were the door. This is the building.
The 0% interest period ends
The exit plan fires
The balances move on a schedule that was written before round one ever went out.
Term loans FIXED
One lump sum, repaid on a fixed schedule the business can plan around.
+
Business lines of credit REVOLVING
Capital the business can pull from and pay back without reapplying.
+
SBA 7(a) PRIME-RANGE
Long duration lending
Underwritten on the business file that phase three built.
Operator File · REF-002Current → Target
InquiriesSCATTERED→MANAGED
LimitsSTARTER→COMPARABLE TIER
Bank RatingNONE→LOW 5
Business FileINVISIBLE→SBSS 160+
Six months earlier, every line on that file read the other way. Nothing on it moved by accident.
Outcome.Bankable. For good.
Term loans, business lines of credit, and SBA lending at prime-range rates... available to the business, on the business.
The products
What the stacks are built from.
Four capital products, each one entering at a different point in the engagement. Which of them a file can carry is decided by the file and the bank, never by us.
0% Business Credit Cards
The opening rounds. Applications go out sequenced by bureau and spacing, and every limit that lands becomes a comparable-limit signal the next bank reads.
Limits build by round
Business Lines of Credit
Revolving capital the business can draw, repay, and draw against again. Underwritten off business documentation, so it runs on a different lane than the personal profile.
Revolving · reusable
Term Loans
Fixed capital on a set schedule, amortizing down from the first payment. These come into range once the business file can be underwritten on its own strength.
Amortizing
SBA 7(a)
The graduation product. Long duration at prime-range rates, and the reason the business scores get built in parallel while the card rounds are still running.
Prime-range · long term
The track record
500+Clients
$100M+Accessed for Clients
ANDREW · $524,500 · UNDER 4 MONTHSBRANDY · $222,000 · 9 APPROVALSBRANDY · $80,000 IN THE FIRST 48 HOURSERWIN · $45,000 · 7 DAYSFRANK · $350,000 SBA · A LATER ROUNDDR. TRUONG · FUNDED AFTER TWO COMPANIES SAID NO
In their own words
Hear what some of our clients have to say.
Every number below was verified against the client's own capital stack. Press play and hear it from them.
$524,500Total Funded
Andrew M.Business Owner · Orlando, FL
"They got me over half a million in total funding. Started with 0% cards, then layered in loans and lines of credit. Two rounds, eight products, all strategic."
$249,500Total Funded
Menard S.Real Estate Investor · Hartford, CT
"Everything you said you would do actually worked like a charm. I was surprised when we got some high limits. You just got to trust the process."
$222,000Total Funded
Brandy E.Med Spa Owner · Philadelphia, PA
"I don't think I would have had the connections, the relationships, and the organization to get to where I am without you guys."
$184,000Total Funded
Dr. TruongHealthcare Professional · Florida
"Having lines of credit and funding help not only me but every business to expand. That is very useful."
Verified reviews
Real reviews from clients of Stacking Capital.
Every review below is a verified Trustpilot review from a Stacking Capital client, published under their own name.
VERIFIED TRUSTPILOT REVIEWS
In writing
One hundred thousand dollars. Minimum.
Qualified clients who complete the program access at least $100,000 in funding, and that number is written into the agreement before you pay us a dollar.
Ask the last funding company you spoke to if they'll sign an agreement with that number in it.
Every plan gets built, reviewed, and signed off inside the firm. None of it is offshore, and none of it is a chatbot.
Your capital advisor1:1 US-Based Advisor
Every application live on Zoom, direct line for the whole engagement.
+
PPFounderPatrick Pychynski
Reviews every funding plan with the capital advisors and senior management each morning, and signs off before it ships.
+
FulfillmentDirector of Fulfillment
Second set of senior eyes on every plan before it runs.
Patrick P.CEO & Founder
Johnny R.Managing Partner
Daniel B.Managing Partner
Jah P.Managing Partner
Jade G.Partner & Lead Advisor
Brad R.Partner & Lead Advisor
Don V.Partner & Lead Advisor
GiulianaCapital Advisor
Javier C.Capital Advisor
Lauren G.Capital Advisor
Casey O.Capital Advisor
Craig C.Capital Advisor
Via R.Capital Advisor
Eric S.Capital Advisor
Jeremiah D.Capital Advisor
Thamires C.Capital Advisor
Tyler M.Capital Advisor
Xavier M.Capital Advisor
Yamil D.Capital Advisor
Drew F.Appointment Coordinator
WEEKLY CADENCELIVE ON ZOOMSPOUSE OR PARTNER INCLUDED
From the founder
I got burned by three funding companies before I ever started one.
I was running a metal recycling business doing seven figures, I needed capital, and every company I hired had the same model: get paid, move fast, disappear.
So during the pandemic I spent fifty thousand dollars learning how business funding actually works, started doing it for friends, and then an ecommerce company hired me to handle their clients' funding because their own team couldn't execute. That became Stacking Capital.
Every funding plan we ship still crosses my desk. That's not a growth strategy. It's the only way I know to keep the promise on this page.
Patrick PychynskiCEO & Founder of Stacking Capital
Straight answers
Questions we get on every call.
Am I getting a loan, or am I getting credit cards?
Cards first. Then the loans the cards make possible.
Round one is 0% business credit cards. That is the fastest liquid capital a prepared profile can reach, and more than that, it is how an account gets opened inside a tier one bank. Once that account reports on time for a few cycles, the bank that issued the card is the same bank you go back to for a line of credit or a term loan, and for SBA money once the file carries it. You walk in with a history instead of an application.
That is the sequence, and it only runs in that order.
Plenty of files are not ready for round one on day one. Utilization sitting too high is the usual reason, and the move is sometimes a low interest personal loan used to pay that utilization down, which puts the profile back in the range the card issuers underwrite to before a single business application goes out. Whether that applies to you depends on what your report actually says. There is no one shape this takes.
That is what the Bankable Blueprint call is for. We read the file and tell you which version of the sequence yours needs.
What does it cost, and why do I pay before anything gets filed?
A flat fee for the engagement, and you get the exact number on your call once somebody has read your profile. No percentage on the back end.
Now, "nothing up front, we only get paid when you get funded" sounds like the aligned offer. I understand the appeal. So look at what that model actually pays a person to do.
Most of the shops running it are a year old and one person deep. They want your credit profile and, in a lot of cases, your power of attorney, so they can shotgun applications at as many banks as possible and see what sticks. Whether anything comes back at 0% does not change their invoice. They take the same ten percent on a charge card, on a personal loan, on a personal credit card, on a merchant cash advance. Anything with a number attached to it.
And they cannot afford to work any other way. Every hour spent clearing your compliance items or waiting on your utilization is an hour they are not earning. The next file pays better. It is a volume business, and you are the volume.
Now grant them their best case. They place $100,000 and invoice you $10,000. But if your profile could carry $100,000 exactly as it sat, you never needed them. You needed an afternoon and a few YouTube videos. AND THAT IS THE BEST CASE.
The likely case is a burned profile and an invoice.
So the fee is up front because the work is up front. Thirty to forty five days optimizing the profile before anything gets filed, then rounds sequenced roughly every thirty to sixty days across a six to twelve month engagement, each one spaced by what the file can carry after the last. That is what you are buying. Filling out the application is the easy part.
How many inquiries does this put on my report, and what does that do to my score?
More people ask this than ask whether they'll get approved at all, and that's the right instinct.
Fewer pulls than doing it yourself. Different banks read different bureaus, and several will approve two cards on a single pull when the applications go in together, so the order decides how many pulls it takes to reach the same limits. After an approval lands, the hard inquiry behind it comes off. The ones that come off are hard inquiries that never became an open account, which is most of what's sitting on a file by the time somebody calls us.
Several banks also cap how much recent activity they'll look past, and this is the part that actually costs money. Too many pulls or too many new accounts in the window they look at and you get declined on the rule, not on your score. So a wasted inquiry doesn't just lose you that approval. It makes the correct one harder to get two months from now. It eats the file.
That's what the sequence buys you. Capacity.
Will any of this show up on my personal credit?
No. The 0% business cards we go after do not report to your personal profile at all.
That is not a footnote, it is the engine. A business card that reports personally drives your utilization up, pulls your score down, and stalls the next round for months. It is the fastest way to break a sequence that was working. Some issuers do it and we do not apply to them, and if another shop is filing on your behalf, which cards they are filing is the first thing you should make them show you.
Because the account never lands on your personal file, the hard inquiry that produced it does not have to stay there either. An inquiry with no open account attached to it can be removed. That is the mechanism that lets us go back for another round, and another, without the profile degrading a little more each time you use it.
A client watched his score drop eighteen points in a day because a business card he had opened on his own reported at 75% utilization. Nobody told him it would. Which cards, in which order, is the answer to a question most business owners never know to ask.
What would you be doing that I couldn't just do on my own?
You could do some of it. Some people do.
This is a white glove engagement for business owners who would rather spend their time running the business than learning an industry. What you are buying is somebody who already knows where the landmines sit: which issuers report business cards personally, which ones approve two on one credit pull, what order a file has to be worked in, what a bank reads before it ever gets to your revenue. None of that is published anywhere. It comes from watching credit profiles land every week, for years, across more industries than I could list here.
And look at how we get paid, because it decides everything above it. One flat fee. The more capital we help you access, the cheaper that capital gets. A shop taking ten to twenty percent of what it places is the exact inverse: every additional dollar it finds you costs you more. Ours is the only version where our upside and your cost of capital move the same direction.
You will have one funding advisor, US based, the same person from your first call through your last round. Nothing gets handed to a fulfillment team you have never met. There is a published number and a real office in West Palm Beach if you want to check it, and every active file is read each morning by five or more advisors before anybody contacts a client.
So what people are actually buying is the long game: a personal profile that survives the process, and a business strong enough that a bank will lend to it at prime. The lowest blended rate across the whole stack is worth more than the fastest yes on one card.
What do I actually have to do?
Show up and share your screen. And don't open new credit while we're working.
Applications get done live on Zoom with you watching. You'll never get a text saying something was submitted under your name.
And there's a mechanical reason for that, not just a trust one. The banks got strict about IP address and geolocation on business applications. It has to come from your device, in your location, or you get auto-denied or approved for a fraction of what the file could carry. So you click the buttons. We tell you which button, in which order, and what each field is actually asking.
Some shops file under your name while you're not even on the call. We don't get that option, because the bank won't take the application from anybody but you.
Between rounds you sit still. No new cards and no new loans, and nothing large parked on a card that's about to get pulled.
Bring your spouse or business partner to the call. They're included in the engagement at no extra cost, personal credit gets pulled, and it's a two person decision in most households anyway.
What do I need to qualify? Do you need tax returns?
For round one, no. The 0% business cards run off your personal profile, so the age of the LLC doesn't decide it, and nobody is asking you for tax returns yet.
Documents come in later, for the bank lines and the SBA products, and getting that paperwork in order is part of the six months.
A score on its own decides very little. All it does is summarize history, and history is not the same thing as capacity.
What a bank reads is the highest limit already sitting on your file and who issued it, how your utilization is split across accounts, how long the file has been open, and what's been pulled recently. Thin files with clean numbers get declined every day of the week. That's what the first call is for. We read the report with you and tell you which of those is in the way.
How long before I see funding, and how many rounds fit in six months?
Round one runs as soon as your file is ready, not at the end. An owner told me this summer he'd assumed the six months was all preparation and the money came last. It's the other way around.
What sets the wait is your file. Utilization has to come down, the compliance items have to clear, accounts have to season, and the file has to read the same on every record a bank pulls. An application sent before that is the one mistake you can't undo, because the approval you burn is the one you needed.
Rounds are spaced by what the file can carry, not by a calendar we hand you, and the gap between them is when the inquiry cleanup and the credit gardening happen. Anyone quoting you a fixed number of rounds before reading your report is quoting you a brochure.
And the six months doesn't start when you sign. It starts when we go for funding. If your profile needs work first, that time doesn't come out of your engagement. You get the full run of rounds either way.
It's 0% now. What happens when it isn't?
0% is short term capital. It runs twelve to eighteen months depending on the issuer and then it prices like any other card. Anyone telling you otherwise is selling you round one and nothing behind it.
So treat that window as runway, not as the product. While those cards are seasoning, the other half of the engagement is running in parallel: the compliance items, the reporting tradelines, the business credit file that decides whether a bank will lend to the company on its own name. By the time that date arrives, the balance needs somewhere cheaper to go.
There are two places it can go. Inside the card, if you are eleven months in and the issuer has a second business card in its lineup, those limits can combine onto the new one and the clock restarts at 0% on the whole balance. Outside it, the bank line or the term loan the last six months were building toward, which is the real exit and the reason none of this was ever about credit cards.
That is what bankable buys. The next time the business needs capital you are not reaching for a merchant cash advance or your own personal cards. You are calling a bank that already knows the file.
What if the approvals don't come?
The first answer is that we try not to let it get that far. We read your credit report on the call, before anyone signs anything, and if the file can't support what you're after right now we say so there, along with what would have to change. Turning people away is cheaper for both of us than finding out in month three.
Past that, the engagement doesn't run on a date. The client agreement sets a written minimum of $100,000 for qualified clients who complete the program, and how that applies to your file gets walked through on the call, before you sign anything.
There are conditions and they're not fine print. Attend the calls. Follow the plan. Don't terrorize your credit profile while we're optimizing it.
And ask the last company you spoke to whether they'll put a number in the agreement before you ever apply. Most of them can't. Their model doesn't let them.
You've seen enough. It's time to speak with an advisor.
Pick your number below and a funding advisor goes through your credit profile and your revenue with you, then tells you what your file can realistically support. If it isn't a fit, you'll hear that on the same call.
Roughly what does the business do in revenue a year?
We're not asking this to push you into an MCA. We steer business owners away from those completely.
Your business
What's the name of your business?
Please enter your business name.
Your business
What industry are you in?
Almost there
What's the capital for? Select all that apply
You can skip this, but the plans we build from a few sentences are noticeably better.
Your funding goal
How much funding are you looking to access?
We help business owners access $100K to $500K at 0% to low interest, then make the business bankable.
Your credit
What's your utilization rate across all your personal revolving credit?
For example, $50,000 in total limits across your cards with a $5,000 balance is a 10% utilization rate.
Your credit
Any missed or late payments in the last 12 months?
A straight answer helps us plan. Clean recent history opens more doors, faster.
You're qualified
Pick a time for your Bankable Blueprint Call.
On this call, a real US-based advisor maps out the exact strategy and sequence to secure six figures of 0% and low-interest capital for your business. Pick a time you can actually make.
Real, U.S.-based capital advisors
Loading available times...
Then this isn't the right time.
The advisory only helps when that monthly number is comfortable, not tight. Signing up while cash is thin is how business owners end up worse off, and we're not going to put you there. When the business can carry it, come back and we'll build your plan.




 Patrick P.
 Johnny R.
 Daniel B.
 Jah P.
 Jade G.
 Brad R.
 Don V.
 Giuliana
 Javier C.
 Lauren G.
 Casey O.
 Craig C.
 Via R.
 Eric S.
 Jeremiah D.
 Thamires C.
 Tyler M.
 Xavier M.
 Yamil D.
 Drew F.